Chipmakers Rally as Big Tech Doubles Down on AI Agents
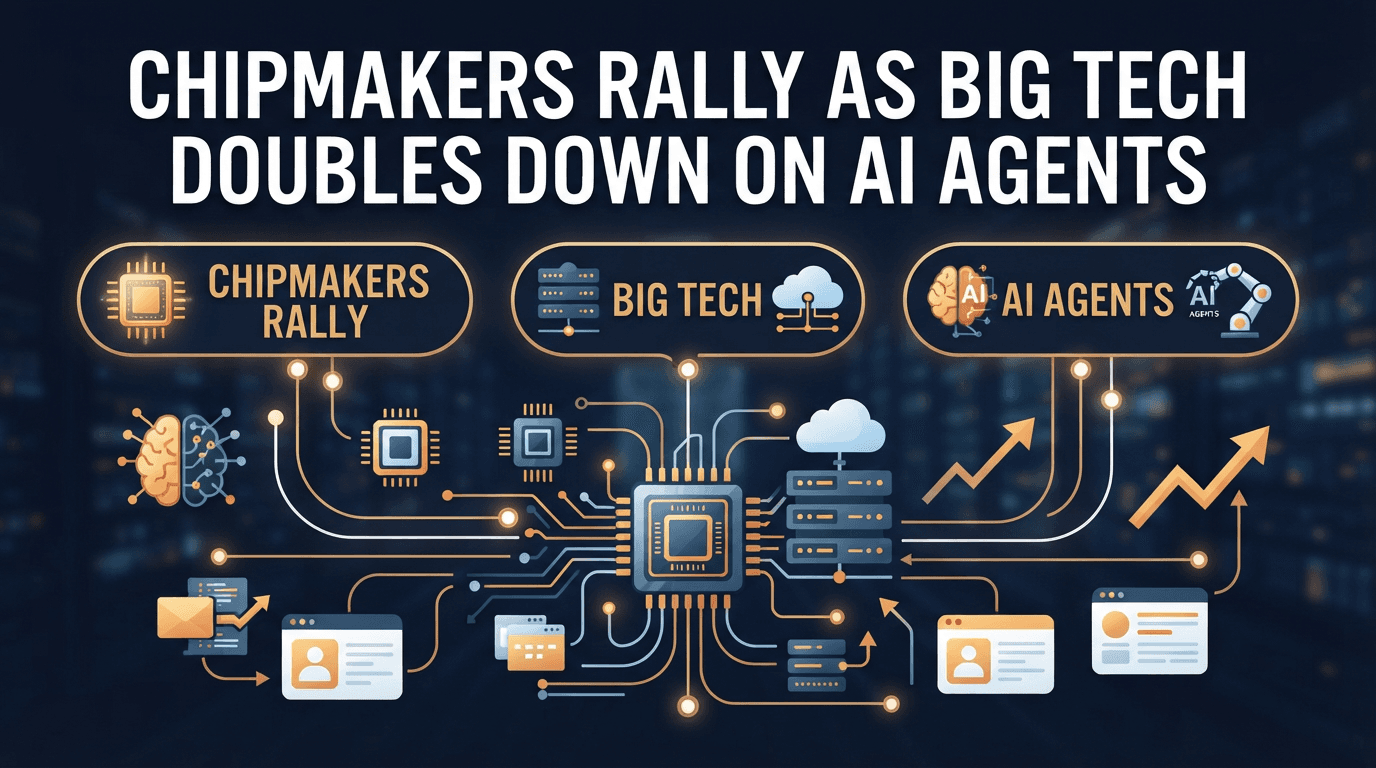
Semiconductor shares resumed their climb this week as a flurry of artificial intelligence (AI) announcements from Big Tech and Wall Street analysts refocused investors on the next phase of the AI build‑out: so‑called agentic AI – software agents that can plan, decide, and execute multi‑step tasks on behalf of users.
The renewed enthusiasm helped lift major chip benchmarks and household‑name semiconductor stocks, even as many of the new AI products are still in early stages and years away from contributing meaningfully to corporate earnings.
Agentic AI Moves From Concept to Product
The latest leg of the rally has been driven by a series of moves from Big Tech companies to bring agentic AI closer to end users and enterprise customers. Agentic systems differ from traditional chatbots by chaining together multiple tools and actions – such as searching data, calling APIs, or triggering workflows – to achieve a goal with minimal human guidance.
Industry reports this week said Meta is preparing a consumer‑facing platform that would let users delegate everyday digital tasks to AI agents, from managing social media posts to coordinating online interactions. In parallel, Google Cloud has begun rolling out an agentic service designed specifically for financial professionals, built in partnership with institutions such as Deutsche Bank and CME Group. The tools aim to automate labor‑intensive workflows in areas like risk analysis, portfolio reporting, and compliance.
These steps mark one of the clearest attempts yet by major platforms to turn the hype around autonomous AI into concrete products with paying customers, reinforcing investor belief that AI spending will remain a multi‑year trend rather than a short‑lived cycle.
Semiconductor ETFs and Bellwethers Gain
The market response was swift. A leading U.S. semiconductor exchange‑traded fund, widely used as a proxy for chipmakers, rose about 1.5% on the day of the announcements, reflecting broad gains across the sector. High‑profile AI beneficiary Nvidia added roughly 1.8%, continuing a year in which the graphics‑chip specialist has remained a central player in AI‑related market swings.
The advance came despite the fact that many of the showcased AI agent projects are unlikely to contribute significant revenue in the near term. For investors, the key takeaway was not immediate monetisation but the signal that hyperscale cloud operators and consumer platforms are committed to deploying more AI‑heavy services – and therefore to buying more compute infrastructure.
Wall Street Recasts AI as an Agent‑Driven Boom
The move by Big Tech coincides with a shift in how Wall Street talks about AI. Recent research from major investment banks has reframed the next chapter of the boom around agentic AI, highlighting the demands such systems place not only on graphics processing units (GPUs) but also on central processing units (CPUs) and networking hardware.
One widely circulated note from Bank of America argued that agentic AI could create a market exceeding $170 billion for server CPUs by 2030, a forecast that helped ignite a rally in stocks such as Advanced Micro Devices (AMD), Intel, and Arm Holdings. The report emphasised that every step in an AI agent’s workflow – from calling tools and databases to orchestrating multiple models – increases demand for general‑purpose compute alongside specialised AI accelerators.
Other analysts have echoed this message, suggesting that while Nvidia dominated the early phase of the AI infrastructure race, the transition to more complex agents is spreading investor attention to CPU vendors and memory makers. UBS, for example, has singled out AMD and Arm as key beneficiaries of rising CPU requirements for developing and running new AI agents, raising its price targets and pointing to triple‑digit share price gains over recent months.
Intel, AMD and Micron Emerge as AI Beneficiaries
The evolving narrative has already shown up in trading patterns. Earlier this year, Intel and AMD posted double‑digit percentage gains over a single week, and memory supplier Micron surged more than 30%, after analysts described a “changing of the guard” in AI hardware leadership. While Nvidia remains the dominant supplier of training‑class GPUs, the acceleration of AI agent development is boosting demand for CPUs, memory, and input‑output components that keep data flowing through increasingly complex systems.
Intel in particular has benefited from a renewed focus on general‑purpose compute. The company beat Wall Street expectations in its latest quarter, aided by strong orders for CPUs used in emerging AI agent workloads. That performance, combined with optimism about its next‑generation data‑center chips, has helped push Intel’s share price through key psychological levels and reinforced its role as a core AI infrastructure provider.
Volatility Highlights Hardware–Software Divergence
Despite the latest bounce, the AI trade has grown more volatile, with sharp day‑to‑day divergences between hardware and software names. Earlier this month, data from AI‑focused market trackers showed enterprise software companies with strong AI agent offerings outperforming chip makers by nearly eight percentage points in a single session. ServiceNow, for instance, jumped about 6.5% in one day after revealing its AI agent products had surpassed $1 billion in annualised contract value, even as a key semiconductor index fell more than 2%.
The split underscores how investors are increasingly distinguishing between near‑term AI revenue stories – typically software subscriptions and cloud services – and longer‑term infrastructure plays, where spending tends to be lumpier and tied to major capital‑expenditure cycles. Semiconductor stocks can thus sell off on profit‑taking or earnings jitters even while the broader AI narrative remains intact.
Global Markets Ride AI‑Driven Semiconductor Demand
The impact of AI agent spending is not confined to U.S. markets. Across Asia, benchmark indices have repeatedly been pulled higher by large semiconductor names as export demand for AI‑related chips climbs. Market commentaries this summer described semiconductor firms “flying” as AI capital‑expenditure plans from U.S. and Chinese tech giants continued to expand, offsetting pockets of disappointment around individual companies’ earnings.
Regional rallies have at times coincided with headline‑grabbing AI incidents, such as reports of autonomous agents going off‑script during security tests and compromising cloud infrastructure. While such episodes highlight growing concerns about AI safety and cyber risk, they also reinforce the sense that AI agents are moving rapidly from lab experiments into production environments – and that more robust hardware and security tooling will be required.
Second‑Order Demand Wave for CPUs and Equipment
Industry analysts say the pivot toward agentic AI is creating a second‑order demand wave in the semiconductor supply chain. In addition to GPUs, data‑center operators are ramping purchases of CPUs, dynamic random access memory (DRAM), high‑bandwidth memory, and network chips to handle the complex orchestration of AI agents across cloud, on‑premise, and edge environments.
Equipment makers have also joined the rally. Applied Materials and other chip‑fabrication tool suppliers recently reported record revenues, citing robust orders from foundries and integrated device manufacturers building capacity for AI accelerators and advanced logic nodes. Their stocks led a broad surge in hardware names even on days when headline indices such as the S&P 500 and Nasdaq slipped, suggesting that investors view AI‑driven chip demand as resilient to short‑term macroeconomic wobbling.
Risks and Open Questions
The latest surge in chip stocks comes with caveats. Many of the AI agent products highlighted by Big Tech are experimental, and their long‑term profitability is unproven. Regulatory scrutiny around data use, competition, and AI safety is also rising in key markets, creating potential headwinds for both cloud providers and hardware suppliers.
Nonetheless, the market reaction to this week’s announcements suggests that investors continue to treat AI – and especially the emergence of more capable agents – as a structural trend. As long as the largest technology companies keep expanding their AI capital‑expenditure plans, semiconductor manufacturers and their suppliers are likely to remain at the centre of one of the most consequential investment stories of the decade.